Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
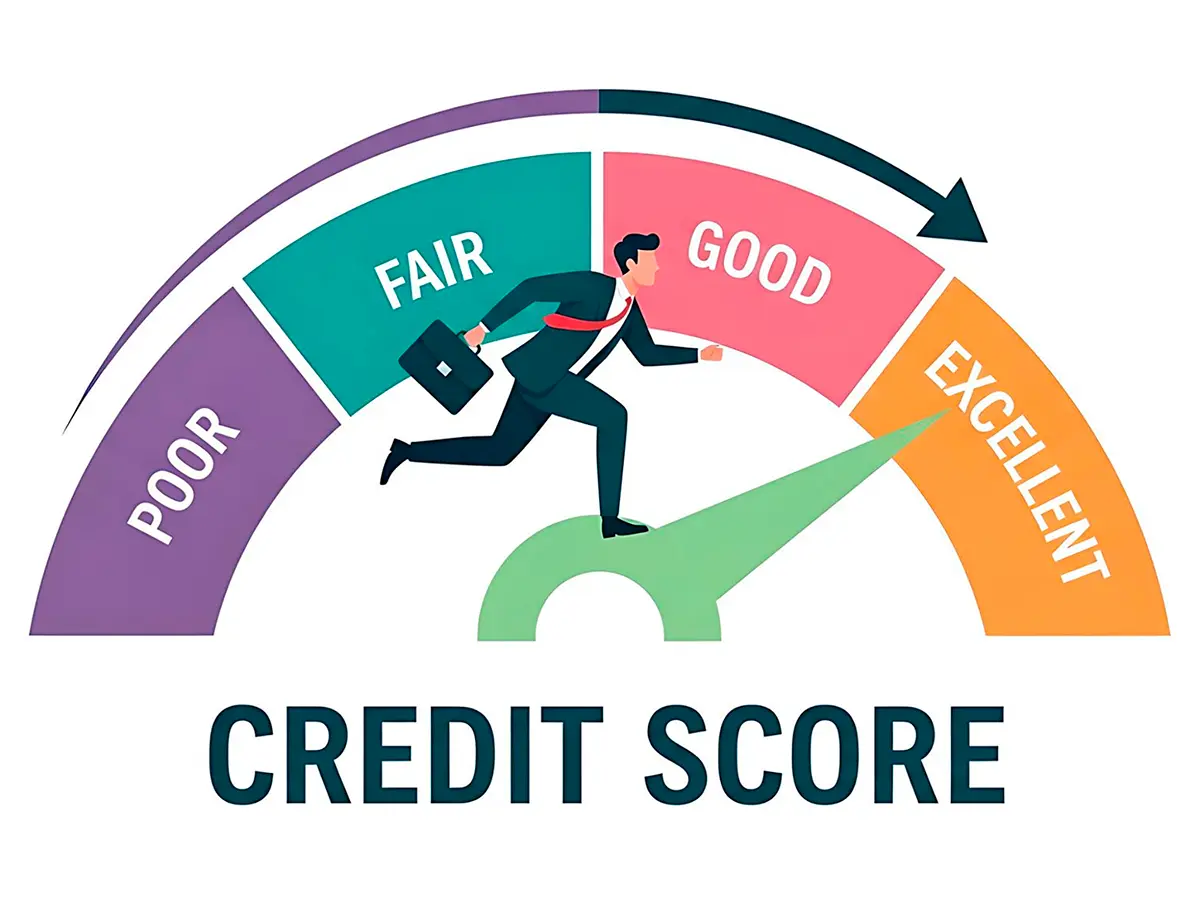
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
ways to improve credit that actually work
Your score moves most when you focus on cause-and-effect, not rumors. Let's separate myth from fact and choose actions by priority so you see a real outcome, not just effort.
Start with the highest-impact moves
- Pay on time, every time. Set autopay for at least the minimum and calendar a second manual payment for full payoff. Priority: highest. Outcome: steady gains and protection from the biggest score killer.
- Lower your utilization. Keep reported balances below 30% of limits - under 10% is stronger. Pay before the statement date, split large purchases across cycles, or request a credit-line increase (without new spending). Outcome: faster score bumps within one to two cycles.
- Keep aged accounts open. Closing a long, fee-free card can shrink available credit and shorten history. If a fee card no longer fits, ask for a no-fee downgrade instead.
- Fix errors on your reports. Pull free reports and dispute inaccuracies; even a misreported late can hold scores down. Clean data equals fair credit.
Myth vs. fact - quick checks
- Myth: Carrying a balance builds credit. Fact: Paying in full proves reliability and avoids interest; reporting a small balance is optional, not required.
- Myth: Closing unused cards will boost your score. Fact: It often hurts by raising utilization and trimming account age.
- Myth: Checking your own score lowers it. Fact: Soft pulls don't affect scores; hard inquiries do, but rate-shopping windows usually count as one.
Build positive history deliberately
- Secured card, used lightly. Small deposit, one or two recurring bills, autopay in full. After 6 - 12 months, ask for graduation.
- Credit-builder loan. Fixed payments saved in a locked account and reported monthly; you get the funds at the end and a track record along the way.
- Authorized user (carefully). Join a well-managed, low-utilization, long-aged card from someone you trust; confirm the issuer reports authorized users.
- Report rent or utilities. Some services add these to your file; not all scores weigh them equally, but the added history can still help.
Real-world moment: last spring you paid your card twice a month, kept utilization under 10%, and a landlord cut your deposit by $400 after a soft check showed improvement. Small systems, big outcome.
Handle debt strategically
- Avalanche vs. snowball. Mathematically, avalanche (highest APR first) wins on interest; snowball (smallest balance first) can win on motivation. Either path is valid if you stick to it.
- Negotiate. Ask for APR reductions, hardship plans, or settlement-in-full-with-fees-waived - get agreements in writing to avoid surprise marks.
- After payoff, keep the line open unless fees bite. A zero-balance, active card supports utilization and age.
Check, track, and protect
- Set balance and due-date alerts; catch spikes early.
- Review reports regularly; freeze your credit if fraud appears, then dispute fast.
Credit grows from habits, not hacks. Prioritize on-time payments and low utilization, layer in clean reports and positive history, and give it a few cycles. The outcome you're after - lower rates, easier approvals, better terms - arrives steadily, even if some prefer a different route to get there.
Nothing will raise your credit score faster or more effectively than paying bills on time and using your credit cards judiciously.
1. Pay your bills on time. The single biggest factor in your credit score is your payment history. Making on-time payments, even if you can only make the ...
Reduce the amount of debt you owe - Keep balances low on credit cards and other revolving credit - Pay off debt rather than moving it around - Don't close ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.